

Blogs
PW Consulting: Office Storage Market Hits USD 3.15 Billion in 2025, Projected 7.9% CAGR to 2032
By PW Consulting, 2026-09-16
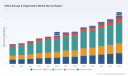
Unlocking Strategic Value in the Office Storage & Organization Market: A 2026 Executive Briefing
The modern workplace is undergoing a structural transformation. As hybrid work models solidify and organizations rethink physical footprint efficiency, the Office Storage & Organization Market has emerged as a critical infrastructure layer for operational productivity, compliance, and spatial optimization. For executive leadership, facility managers, and procurement strategists, the question is no longer whether to invest in smarter storage ecosystems, but how to align those investments with long-term growth trajectories, cost containment mandates, and evolving workplace safety mandates.
Our latest market research publication delivers a comprehensive, data-grounded assessment of this sector, mapping historical performance, forward-looking demand signals, competitive positioning, and the macroeconomic forces reshaping procurement decisions. This briefing outlines the strategic architecture of the study and explains why it serves as an essential decision-support tool for 2026 planning cycles.
Macro Trajectory: Scaling Demand in a Shifting Workspace Economy
Over the past half-decade, the office storage and organization sector has demonstrated consistent expansion, reflecting broader trends in workplace rationalization, inventory visibility, and the formalization of remote and hybrid work environments. Historical tracking from 2020 through 2025 shows a steady climb in market revenue, with the sector moving from approximately 2.18 billion USD to 3.15 billion USD by the base year. This upward arc underscores a sustained organizational appetite for structured storage solutions that support document management, equipment housing, and spatial decluttering across corporate and decentralized work settings.
Looking ahead, the forecast horizon through 2032 projects continued momentum, with the market anticipated to reach 5.34 billion USD by the close of the period. The implied compound annual growth rate of 7.9 percent signals a sector that is not merely recovering from post-pandemic workspace adjustments, but actively re-architecting how organizations store, access, and manage physical assets. This growth trajectory carries meaningful implications for capital allocation, supplier relationship management, and facility planning. Decision-makers who internalize the pace and shape of this expansion can better time procurement cycles, negotiate volume commitments, and align storage investments with broader workplace modernization roadmaps.
Office Furniture Market
Structural Shifts Driving Buyer Behavior and Product Preference
The sector’s evolution is being shaped by several intersecting forces that alter both demand composition and supplier strategy. First, the proliferation of remote and hybrid work arrangements has expanded the addressable footprint for home office storage and organization products. As professionals convert residential spaces into functional work environments, demand for scalable, aesthetically cohesive, and ergonomically mindful storage units has grown. This shift is not simply a residential trend; it reverberates through corporate procurement as employers extend stipends, equipment packages, and standardized organization kits to distributed workforces.
Second, workplace safety and regulatory expectations are tightening the specification criteria for storage infrastructure. Occupational safety regulations increasingly require storage units to meet defined load-bearing thresholds and fire-resistance standards. These requirements elevate the importance of compliance-ready designs, pushing buyers toward suppliers that can document material certifications, structural testing, and adherence to regional building and fire codes. In practice, this means procurement teams must evaluate not only storage capacity and modularity, but also the evidentiary trail that supports regulatory conformity.
Third, cost dynamics are introducing complexity into margin planning and pricing strategy. Raw material volatility affecting steel, wood composites, and engineered plastics has constrained manufacturers’ ability to absorb cost fluctuations without adjusting product pricing or reprioritizing feature sets. Simultaneously, the wood office-furniture producer price index reached elevated levels in mid-2025, creating cost headwinds that ripple through the broader storage and organization supply chain. For buyers, this environment rewards strategic sourcing, multi-supplier diversification, and specification flexibility that preserves functional requirements while mitigating exposure to input-cost spikes.
Finally, financing mechanisms are shaping deployment timing, particularly for small and mid-sized enterprises. In the United States, Small Business Administration 504 loans provide long-term financing pathways for office storage infrastructure investments. This availability can smooth capital expenditure planning, enable phased rollouts, and help organizations align storage upgrades with broader facility improvement programs. Understanding the interplay between financing options and procurement cadence is increasingly relevant for market participants evaluating total cost of ownership rather than upfront price alone.
What the Report Delivers: Operational Intelligence for Procurement and Strategy Teams
This research is structured to move beyond headline figures and provide actionable intelligence that supports real-world decision-making. The study combines quantitative modeling with qualitative assessment, giving readers a multidimensional view of market behavior, supplier capabilities, and demand-side priorities. Key components of the publication include:
- A detailed historical reconstruction of market performance across the 2020–2025 period, establishing a reliable baseline for evaluating growth consistency, demand elasticity, and segment maturation.
- A forward-looking forecast framework extending through 2032, designed to help organizations stress-test procurement assumptions, plan capacity alignment, and anticipate inflection points in adoption.
- An examination of product-type dynamics, contrasting conventional office storage cabinets with mobile shelving systems, including the operational trade-offs that influence selection in different workspace configurations.
- An application-level analysis that disaggregates demand across corporate headquarters, remote home offices, and other deployment contexts, highlighting how use-case requirements shape specification, throughput expectations, and purchase frequency.
- A regional perspective that maps demand distribution and contextual factors across major geographic markets, supporting multinational planning and localization strategies.
- A competitive landscape assessment that profiles leading participants, evaluates strategic positioning, and tracks recent product and catalog developments that signal where the market is heading.
- An integrated review of market concentration indicators, providing context on supplier consolidation, pricing power, and the degree of fragmentation or consolidation that characterizes the sector.
The report is intended for use by strategic procurement leaders, workplace operations executives, financial planners, and market-entry teams who require a structured, evidence-based foundation for evaluating storage and organization investments. Rather than treating the sector as a commoditized furniture category, the study frames it as a functional infrastructure market where compliance, space efficiency, durability, and total cost of ownership carry decisive weight.
Competitive Landscape: Positioning, Innovation, and Recent Market Signals
The competitive environment in office storage and organization reflects a blend of established manufacturers, specialized systems providers, and broad-access retail players. Each category brings a distinct value proposition to buyers, and understanding these differences is essential for evaluating supplier fit, negotiating terms, and building resilient supply chains.
Companies such as Office Furniture EZ operate through a hybrid distribution model that combines physical showroom access with online catalog availability, offering modular furniture, cabinets, and accessories that appeal to buyers seeking visible product interaction and convenient catalog browsing. SHUTER emphasizes manufacturing capability with a focus on modern office storage cabinets, tool storage, and organizational systems built around innovation and durability, positioning itself for customers who prioritize engineered reliability and product evolution. Livinbox enters the space with a design-oriented approach, crafting stylish home and office storage products, plastic containers, organizers, and modular solutions that resonate with buyers balancing aesthetics and practicality. HNI Corporation contributes high-density storage systems and office organization solutions integrated with broader workplace furniture offerings, making it relevant for organizations pursuing space optimization within a unified furniture strategy. Spacesaver Corporation specializes in high-density mobile storage and organization systems, targeting environments where maximizing accessible storage within limited footprints is a core operational requirement.
Additional participants broaden the market’s reach and purchasing pathways. Montel Inc. provides storage and organization solutions tailored to office environments, while The Container Store extends retail and home office storage options that support productivity-focused organization for distributed professionals. Ikea remains a prominent global retailer of affordable, modular office storage and organization products, offering a value-focused entry point for cost-sensitive buyers and standardized deployment scenarios.
Recent company activities reinforce the sector’s dynamic character. In 2026, Office Furniture EZ released its product catalog featuring office storage and organization solutions, while SHUTER issued a 2026 catalog highlighting modern office storage cabinets and organizational systems. Livinbox meanwhile showcased new product lineups at major trade events, signaling continued product refresh activity and an emphasis on visible innovation in storage design and modularity. These developments illustrate how competitors are using catalog expansion and product showcases to capture attention, differentiate capabilities, and align offerings with evolving buyer expectations.
Market concentration data provides additional context for competitive assessment. With a CR3 of 25.0 percent and a CR5 of 30.0 percent, the sector exhibits a moderate degree of consolidation without full concentration at the top. This structure suggests that while leading players hold meaningful share, there remains ample room for specialized suppliers, regional performers, and design- or price-focused entrants to compete on specification, service, and niche application fit. For procurement leaders, this landscape supports a dual strategy: leveraging scale and consistency from established suppliers while preserving flexibility through secondary sources that can address specialized requirements or cost constraints.
Office Storage & Organization Market
Why This Research Matters for 2026 Decision-Making
The strategic value of this study lies in its ability to connect market structure with operational consequence. In 2026, organizations are making decisions under multiple pressures: the need to optimize real estate and workspace utilization, the imperative to maintain compliance with evolving safety standards, the challenge of managing input-cost volatility, and the expectation to support distributed workforces with consistent, reliable storage solutions. A superficial view of the market can lead to under-specification, reactive purchasing, or over-reliance on single-supplier relationships. A structured, evidence-based view enables more disciplined planning.
For procurement and operations leaders, the report provides a basis for comparing product types against actual usage scenarios, weighting durability and compliance alongside capacity and aesthetics, and evaluating supplier portfolios against recent innovation signals. For financial and strategy teams, the forecast framework supports scenario modeling around demand growth, investment timing, and the potential impact of financing instruments on deployment schedules. For market-entry and business development teams, the segmentation and competitive analysis clarifies where differentiation is achievable and which buyer priorities are most likely to shape purchasing decisions over the forecast period.
Equally important, the study helps organizations avoid misreading the market as purely price-driven. While cost remains a central factor, the sector’s trajectory is increasingly defined by functional performance, regulatory readiness, modular flexibility, and the ability to support both centralized and distributed workplace models. Buyers who evaluate storage and organization investments through this broader lens are better positioned to secure long-term value rather than short-term savings that may compromise durability, compliance, or adaptability.
Conclusion: Moving from Awareness to Actionable Intelligence
The Office Storage & Organization Market is expanding at a measured but meaningful pace, shaped by workspace redesign, regulatory compliance, material-cost dynamics, and the continuing normalization of hybrid work. The sector’s projected growth through 2032 reflects an environment in which storage infrastructure is no longer a peripheral procurement category, but a core enabler of productivity, safety, and spatial efficiency.
This research publication is designed to give executives the depth they need to act with confidence. It integrates historical context, forward-looking modeling, competitive profiling, and industry dynamics into a single decision-support framework. To access the full segmentation detail, regional breakdowns, application-level evaluations, and complete competitive intelligence, we invite stakeholders to review the complete report through our official research portal. The full dataset and proprietary analysis are available there for teams ready to translate market insight into structured 2026 and beyond procurement strategies.
For detailed analysis of this topic, please visit the official page: Office Storage & Organization Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Waste Paper Recycling Market to Reach $74.3B by 2032, 5% CAGR
By PW Consulting, 2026-09-16
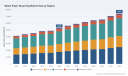
Strategic Intelligence for the Waste Paper Recycling Market: Navigating Growth from 2026 to 2032
The global waste paper recycling industry stands at a critical inflection point. As environmental regulations tighten and corporate sustainability mandates become non-negotiable, the sector is transitioning from a linear waste management model to a circular economy cornerstone. For strategic decision-makers, understanding the trajectory of this market is no longer optional—it is a prerequisite for capital allocation, supply chain resilience, and competitive positioning. This analysis draws upon comprehensive market research to outline the opportunities and risks defining the period from 2026 through 2032.
Market Trajectory: From Recovery to Sustained Expansion
The macroeconomic backdrop for waste paper recycling is characterized by robust historical growth and a confident forecast horizon. Tracing the valuation from the base year 2025 through the forecast period ending in 2032 reveals a sector that has successfully weathered economic volatility to establish a strong upward trend. In 2020, the market valuation stood at approximately 41,500 million USD. Over the subsequent five years, the industry demonstrated resilience, climbing to 48,982.3 million USD by 2024 despite supply chain disruptions and fluctuating raw material costs.
The momentum accelerated leading into the current baseline, with the market size reaching 53,000 million USD in 2025. This growth trajectory is projected to continue, with the valuation expected to breach 56,491.54 million USD in 2026. Looking further ahead, the compound annual growth rate (CAGR) is estimated at 5.0 percent throughout the forecast period. By 2032, the market is anticipated to reach 74,300 million USD. This steady expansion underscores a structural shift in how industries view recovered fiber—not merely as waste, but as a valuable commodity integral to manufacturing supply chains.
Key Growth Drivers and Industry Dynamics
Several converging forces are fueling this expansion. First, the global push toward reducing carbon footprints is driving demand for recycled content in packaging and tissue products. Second, regulatory frameworks in key economic zones are increasingly mandating minimum recycled content thresholds, effectively creating a price floor for recovered paper. Third, technological advancements in sorting and pulping efficiency are lowering the operational costs of recycling facilities, improving margins for processors.
Recent industry data highlights the sensitivity of this market to supply and demand fundamentals. For instance, in March 2026, recovered paper prices for Old Corrugated Containers (OCC) increased due to stronger demand for recycled fiber coupled with tightening supply. Such fluctuations indicate a mature market where inventory management and long-term supply contracts are becoming critical strategic levers. Companies that secure reliable feedstock sources will hold a distinct advantage as competition for high-grade waste paper intensifies.
Segmentation Insights: Where Value is Concentrated
Understanding where value resides within the waste paper recycling ecosystem is essential for targeted investment. The market is segmented by type, application, and region, each presenting unique risk-reward profiles. While specific granular data is reserved for the full report, the broader distribution patterns reveal where strategic focus should be applied.
Material Types and Processing Requirements
The market encompasses various grades of waste paper, each requiring distinct processing technologies. Corrugated cardboard remains a dominant stream due to its prevalence in logistics and e-commerce packaging. High-grade paper and old newspapers or magazines also constitute significant portions of the feedstock mix. Mixed paper presents a more complex challenge due to contamination risks but offers volume potential. The choice of processing equipment—whether shredding, pulping, or baling—depends heavily on the specific material stream a company intends to target. Investing in the wrong technology for a specific paper grade can erode margins quickly.
Application End-Uses
The downstream demand is diversified across several key industries. Packaging represents the largest consumption channel, driven by the retail and e-commerce sectors' relentless demand for sustainable boxes and containers. Construction utilizes recycled fiber for insulation and other materials, while printing and writing applications maintain a steady, albeit slower-growing, demand. The tissue and hygiene sector is another critical consumer of high-quality recycled pulp. Understanding the yield rates and quality specifications required by each application is vital for recyclers aiming to maximize revenue per ton of input material.
Regional Nuances
Geographically, the market is distributed across North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. Asia Pacific, in particular, has shown significant activity due to industrialization and urbanization trends. However, regional regulations regarding waste imports and exports create varying operational landscapes. A strategy that works in North America may not be directly transferable to Latin America or Europe without adjusting for local compliance costs and infrastructure maturity.
Competitive Landscape: Technology Leaders and Strategic Roles
The competitive environment is fragmented but features distinct players who dominate specific niches of the technology stack. The market concentration metrics indicate a moderate level of consolidation, with the top three companies holding a notable share and the top five increasing that presence. This suggests that while there is room for specialized players, scale and technological superiority are becoming increasingly important.
Equipment Manufacturers and Technology Providers
Several key companies define the current equipment landscape, offering solutions that range from primary shredding to complete turnkey recycling lines. WEIMA , based in Germany, focuses on single-shaft shredders such as the WLK 15 and WLK 18 Jumbo models. These are designed for efficient processing of paper, cardboard, and OCC into flakes or pulp, offering customizable configurations for recycling lines. Their technology is critical for initial size reduction and preparation.
In the realm of complete processing facilities, Parason Engineering from India provides turnkey recycled-fiber lines. Their offerings include pulpers, cleaners, screens, and deinking systems for OCC and mixed waste. These lines produce board, liner, newsprint, and tissue at capacities ranging from 8 to 1030 TPD. This breadth allows them to serve both small-scale localized operations and large industrial mills.
For material handling and volume reduction, American Baler Company and Maren Engineering Corporation in the USA are prominent. American Baler specializes in horizontal and two-ram balers engineered for OCC, paper, and cardboard bales, reducing volume and labor in recycling and distribution centers. Maren Engineering complements this with horizontal auto-tie, two-ram, and closed-door balers specifically for OCC and cardboard recycling to flatten material for storage and transport. Efficient baling is crucial for logistics economics, directly impacting the cost of moving recycled fiber to mills.
On the shredding and pre-processing side, BHS-Sonthofen in Germany provides shredders and pre/post-shredding equipment for paper, cardboard, and OCC in recycling applications. Meanwhile, SOYU in China focuses on OCC dry pulping and recycling lines that convert waste paper into recycled pulp with energy-efficient dry processing. This energy efficiency angle is becoming a key differentiator as energy costs rise. Rexon Hydraulics , also based in India, offers automatic horizontal paper balers and recycling machines for cardboard and OCC, catering to the automation needs of modern facilities.
Recent Market Movements
Market activity remains dynamic. In June 2026, ReBAT confirmed its status as an exhibitor at the World of Recycling Expo 2026 in India, showcasing material recycling machinery including waste paper solutions. Such events highlight the ongoing innovation cycle and the importance of industry networking for identifying emerging technologies and partnership opportunities. Participation in major expos often signals a company's commitment to expanding its footprint in high-growth regions.
Waste Paper Reuse Market
Strategic Imperatives for 2026 Decision Makers
For executives and investors looking to navigate this landscape in 2026, several strategic imperatives emerge from the data.
Waste Paper Recycling Market
- Supply Chain Security: With tightening supply noted in recent months, securing long-term contracts with waste generators or establishing owned collection networks is vital. Volatility in OCC prices can impact profitability significantly.
- Technology Alignment: Investing in the right machinery is crucial. Whether it is energy-efficient dry pulping, high-capacity shredding, or automated baling, the technology must match the target material stream and end-use quality requirements.
- Regional Compliance: Navigating the regulatory divergence between regions like Europe, North America, and Asia Pacific requires localized expertise. Compliance costs can vary widely and impact the economic feasibility of cross-border trade in recycled materials.
- Capacity Planning: With the market projected to grow steadily towards 2032, capacity expansion plans must be timed correctly. Overbuilding too early risks underutilization, while delaying risks missing the demand surge driven by sustainability mandates.
Conclusion: The Value of Comprehensive Market Intelligence
The waste paper recycling market offers substantial opportunities for growth, but realizing them requires more than just general industry awareness. It demands a granular understanding of segmentation splits, competitive positioning, regulatory pressures, and technological capabilities. The macroeconomic numbers tell a story of growth, but the operational details tell the story of profitability.
This overview serves as a high-level indicator of the trends shaping the industry. However, the complex interplay between material grades, regional regulations, and specific equipment specifications requires deeper analysis. For organizations aiming to make informed capital deployment decisions or strategic partnerships in this sector, access to detailed segmentation data, company profiles, and risk assessments is indispensable.
To fully leverage the 5.0 percent CAGR opportunity and navigate the competitive landscape defined by key players like WEIMA, Parason, and others, stakeholders need the complete intelligence picture. The full market research study provides the necessary depth on segmentation values, historical trends, and forecast nuances to build a robust strategy for the 2026 to 2032 period.
For detailed analysis of this topic, please visit the official page: Waste Paper Recycling Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Ring Laser Gyroscope Market to Hit $10.9B by 2032, 9.2% CAGR
By PW Consulting, 2026-09-16
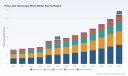
Navigating Precision: The Strategic Imperative of the Ring Laser Gyroscope Market in 2026
Introduction: The Precision Economy
In the landscape of modern navigation, stability is not merely a preference; it is a fundamental requirement for operational success. The Ring Laser Gyroscope, or RLG, stands as a cornerstone technology within this sector, enabling inertial navigation systems to maintain accuracy without reliance on external signals. As global industries increasingly depend on autonomous platforms, advanced aerospace systems, and secure naval operations, the demand for high-fidelity rotational sensing has escalated. This shift represents more than a technical evolution; it signals a substantial economic opportunity that demands rigorous analysis and strategic foresight.
For enterprise leaders operating in aerospace, defense, automotive, and marine sectors, understanding the trajectory of the RLG market is critical. The period extending from 2026 through 2032 promises to be a transformative era defined by technological maturation, supply chain realignment, and heightened competition. Our latest market research publication is designed to cut through the noise, offering a comprehensive view of where value is being created and how competitive dynamics are shifting. This article serves as a strategic primer, outlining the macro-economic currents and competitive forces that will define the landscape, while highlighting the depth of intelligence available in the full report.
Market Trajectory and Economic Scale
The financial magnitude of the Ring Laser Gyroscope sector underscores its importance as a strategic investment area. Historical data from 2020 through 2025 reveals a consistent upward trend, reflecting the gradual integration of RLG technology into more complex and demanding applications. The market valuation has demonstrated resilience and growth, culminating in a significant baseline as we enter the forecast period. Looking ahead, the revenue projections indicate a robust expansion trajectory that extends well into the next decade.
According to our analysis, the global market revenue is poised to grow from a established base in the mid-five billion USD range in 2026 to nearly eleven billion USD by 3032. This growth is not linear but reflects compounding demand drivers across multiple high-value industries. The Compound Annual Growth Rate during this forecast window is estimated at 9.2 percent, signaling a healthy velocity that outpaces many traditional industrial sectors. This rate suggests that capital allocated toward RLG-related technologies or capabilities has the potential for substantial return, provided the investment is targeted correctly within the value chain.
Laser Rangefinder Market
However, aggregate numbers only tell part of the story. The real strategic value lies in understanding the composition of this growth. The revenue stream is not uniform; it is distributed across varying technological configurations and end-use sectors, each with its own risk profile and growth potential. Decision-makers need to know which segments are driving the headline figures and which are lagging, without necessarily revealing the specific numerical breakdowns that could be used by competitors. Our full report dissects these variances, allowing clients to benchmark their position against the broader market rhythm without exposing sensitive comparative data publicly.
Competitive Landscape and Key Players
The structure of the RLG market is characterized by a moderate level of concentration, where a handful of specialized entities hold significant influence over supply chains and technological standards. With a CR3 concentration ratio hovering around 45 percent and a CR5 near 55 percent, the market remains accessible yet competitive. This structure implies that while large players set the tempo, there is room for specialized innovators and component suppliers to capture value through niche excellence. Understanding the identity and capability of these key players is essential for partnership strategy, procurement decisions, and competitive positioning.
Several companies have emerged as pivotal actors in this ecosystem, each contributing distinct value propositions. G&H Products, based in California, exemplifies the artisanal yet high-precision approach to manufacturing. They design and manufacture RLG frames and optical components by hand, supplying complete RLG component packages. Their operations are deeply entrenched in quality assurance, with facilities certified to ISO9001 and AS9100D standards. Furthermore, their compliance with ITAR legislation and registration with the US government underscores their role in the sensitive defense supply chain. By supplying entire component packages including Zerodur frames and precision mirrors, they occupy a critical upstream position that influences the final performance of the gyroscope.
On the optical component side, Excelitas Technologies Corp., headquartered in Pittsburgh, provides the foundational elements that make high-performance RLGs possible. Their precision mirrors and optics are optimized for RLG applications, achieving micro-roughness below 0.5 Angstrom and low scattering. These technical specifications are not merely marketing claims; they represent the physical limits required for maintaining laser cavity finesse, reported at levels up to 200,000. For system integrators seeking to minimize signal noise and maximize stability, the choice of optical supplier is a critical technical decision that impacts the entire navigation suite's reliability.
Completing the triad of innovation is Micro Magic, also based in the United States. They focus on developing and producing complete RLG-based inertial navigation systems, or INS. Their portfolio includes high-precision models tailored for defense and aerospace platforms. This vertical integration from component to system allows them to address end-user requirements directly. In late 2025, Micro Magic announced the launch of new solid-state RLG models, specifically the G-R90, G-R70, and G-R50. These launches target high-precision INS needs for defense and unmanned platforms, indicating a strategic pivot toward versatile, scalable solutions that can accommodate smaller unmanned aerial vehicles as well as larger defense assets. Tracking such product launches is vital for anticipating shifts in capability availability and pricing pressure.
Industry Dynamics and Supply Chain Considerations
The operational environment for RLG market participants is shaped by a complex interplay of regulatory, technological, and supply chain factors. For manufacturers operating in the United States, particularly those serving defense clients, regulatory compliance is not optional. The requirement to comply with ITAR legislation means that export controls and government registration are integral to business continuity. Companies like G&H Products maintain this status explicitly, which serves as both a barrier to entry for non-compliant competitors and a signal of reliability for government contractors. Understanding the regulatory landscape is necessary for assessing market accessibility and potential geopolitical risks that could disrupt supply.
Supply chain resilience is another critical dynamic. The production of an RLG requires specialized materials and precise manufacturing capabilities that are not easily commoditized. The use of materials like Zerodur for frames, supplied by key component vendors, highlights the dependency on specific material sciences. Any disruption in the supply of these high-grade materials can ripple through the production timeline. Our research delves into the sourcing strategies of major players, examining how they mitigate risk through vertical integration or long-term supplier partnerships. For procurement leaders, identifying single points of failure in the supply chain is a prerequisite for building robust inventory strategies.
Ring Laser Gyroscope (RLG) Market
Technological differentiation remains the primary battleground. While the basic physics of the ring laser gyroscope is established, incremental improvements in cavity performance, thermal stability, and size-weight-power profiles continue to drive market segmentation. The push toward solid-state models, as seen in recent developments, suggests a trend toward reduced maintenance and higher reliability, which is particularly valuable for unmanned systems that may lack onboard maintenance crews. Companies that can offer superior micro-roughness in optics or tighter tolerances in mechanical assembly gain a competitive edge that is difficult to replicate quickly. These technological moats are analyzed in depth to help clients understand where true differentiation lies versus where marketing hype may obscure reality.
Strategic Value for Enterprise Decision-Makers
Access to granular market intelligence provides a distinct advantage in formulation of corporate strategy. For investors, the projected revenue path offers a framework for valuation models, helping to determine whether current market sentiment aligns with fundamental growth drivers. For manufacturers, the segmentation data helps identify whitespace opportunities where competition is less intense but demand is growing. For defense contractors, understanding the supply chain positions of component providers like G&H Products or Excelitas ensures that sourcing strategies are aligned with long-term program requirements.
The full report goes beyond the macro trends summarized here. It provides detailed profiling of the ecosystem, mapping out the capabilities of key players against specific application needs. It examines the regulatory environment not just as a constraint but as a strategic filter that defines who can participate in high-value government contracts. The supply chain analysis extends to identifying potential bottlenecks and opportunities for vertical integration. Furthermore, the application analysis breaks down demand drivers across aerospace, marine, automotive, and other sectors, providing context on which industries are leading adoption and why.
Timing is also a critical component of strategic planning. With the forecast period extending to 2032, organizations need to plan capital expenditures and R&D investments today that will pay off in the latter half of the decade. Knowing when market maturity might lead to price compression allows companies to adjust their margin expectations and shift focus to service-based revenue or system integration. Conversely, identifying emerging segments early allows for first-mover advantages in securing supply contracts or intellectual property positions. The report is designed to support these timeline-dependent decisions with data that is both forward-looking and grounded in historical performance.
Conclusion: The Path Forward
The Ring Laser Gyroscope market stands at a pivotal intersection of technological capability and economic opportunity. The growth trajectory suggests that demand will continue to outpace supply in certain high-precision segments, creating leverage for established players while offering challenges for newcomers. The competitive landscape is defined by specialized firms that combine deep technical expertise with regulatory compliance, creating high barriers to entry that protect incumbents. For enterprise leaders, the ability to navigate this landscape depends on having access to accurate, detailed, and actionable intelligence.
This article has provided a high-level overview of the market dynamics, key participants, and structural factors influencing the sector. However, the true power of this research lies in the detailed data and specific strategic recommendations available in the full publication. To truly understand the nuances of the segmentation splits, the regional dynamics, and the specific financial projections required for robust planning, direct access to the comprehensive dataset is necessary. We invite stakeholders to explore the full report to equip their organizations with the insights needed to thrive in this evolving precision economy. Making informed decisions now will determine competitive positioning for the remainder of the decade and beyond.
For detailed analysis of this topic, please visit the official page: Ring Laser Gyroscope (RLG) Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Automotive Door Handle Sensor Market Hits $2.12B in 2025, Poised for 6.15% CAGR Through 2032
By PW Consulting, 2026-09-16
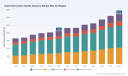
Strategic Intelligence for the Automotive Door Handle Sensors Market: Navigating the 2026–2032 Landscape
The automotive industry is undergoing a profound transformation in how vehicles are accessed, secured, and interacted with. At the heart of this evolution lies a seemingly minor component that carries outsized strategic importance: the door handle sensor. What was once a purely mechanical element has become a critical interface for keyless entry, gesture recognition, and hands-free operation, particularly in electric vehicle platforms where flush and hidden handle designs are increasingly preferred. To support executives, product strategists, and investment analysts in making informed decisions throughout 2026, we have assembled a comprehensive market study on the Automotive Door Handle Sensors Market. This article offers a focused preview of the research, highlights its strategic value, and outlines the operational intelligence contained within the full report.
Why 2026 Marks a Defining Moment for Door Handle Sensor Strategy
The base year of 2025 established a market valuation of approximately 2.12 billion USD, and the trajectory through the forecast window points to steady, compounding expansion. By 2032, the market is projected to reach roughly 3.22 billion USD, reflecting a compound annual growth rate of 6.15 percent over the 2026–2032 period. These figures are not merely backward-looking statistics; they signal a structural shift in vehicle architecture, consumer expectations, and regulatory scrutiny. Automotive door handles are no longer passive hardware. They are becoming integrated sensing nodes that must satisfy demands for reliability, aesthetics, user convenience, and, increasingly, safety compliance.
For decision-makers in 2026, the strategic question is no longer whether door handle sensors will become standard, but how quickly portfolios can adapt to varying sensor technologies, regional regulatory timelines, and OEM customization requirements. The market study is designed to give leaders a clear line of sight into these dynamics, enabling resource allocation that is aligned with long-term revenue opportunities rather than reactive to short-term fluctuations.
What the Research Delivers: Actionable Intelligence Beyond Headline Numbers
The study is built for practical application. It maps the market across sensor types, end-use applications, and geographic regions, while also examining concentration levels among leading suppliers. Rather than presenting static tables, the report translates data into strategic context, helping teams assess where growth is most durable, which applications are gaining traction, and how regional demand profiles differ in pace and character.
Below is a structured preview of the report’s core analytical sections:
- Market sizing and growth trajectory: A multi-year view from historical baseline years through the full forecast period, supporting planning for capacity, investment, and product roadmap decisions.
- Technology segmentation analysis: An evaluation of capacitive, infrared, ultrasonic, and other sensing approaches, with attention to integration complexity, false-trigger resistance, power consumption, and suitability for compact door handle designs.
- Application-driven demand mapping: A breakdown of how keyless entry systems, power door systems, and gesture control systems are shaping sensor requirements across different vehicle segments and OEM priorities.
- Regional demand patterns: A comparative look at how North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa contribute to overall market expansion, with implications for localization, supply planning, and market-entry timing.
- Competitive landscape and concentration: An assessment of market share distribution among leading participants, highlighting the degree of consolidation and the strategic room available for differentiation.
- Regulatory and safety dynamics: A review of policy developments that are reshaping engineering requirements, particularly around hidden or flush door handle designs in electrified platforms.
- Recent industry developments: A timeline-based synthesis of product launches, standards approvals, and investigative activity that are influencing near-term procurement and engineering decisions.
Each section is designed to be referenced independently or read as part of an integrated strategy narrative. The objective is to give automotive suppliers, tier-1 component developers, OEM strategy teams, and investors a reliable basis for scenario planning, risk assessment, and prioritization.
Sensor Technology Choices and the Real-World Trade-Offs They Create
Sensor selection in door handle applications is not a purely technical decision; it is a commercial one. The report examines how different sensing modalities align with distinct vehicle requirements and user experience goals. Capacitive sensing continues to attract strong interest for its ability to support sleek, flush-mounted designs and low-profile integration, especially when combined with gesture recognition and improved resistance to false triggers. Infrared-based solutions offer attractive proximity detection characteristics and can be well suited to specific detection ranges and environmental conditions. Ultrasonic approaches provide an additional pathway for hands-free activation, with relevance to both premium and mass-market vehicle programs. A broader category of alternative sensor designs also exists, often tailored to specialized use cases or OEM-specific integrations.
What matters strategically is that no single technology is universally optimal. The right choice depends on vehicle platform, power budget, aesthetic targets, cost constraints, and the intended user interaction model. The study helps decision-makers compare these trade-offs in a structured way, so that product planning teams can anticipate where demand will concentrate and how supplier capabilities will need to evolve.
Applications Are Reshaping Demand, Not Just Component Specs
Door handle sensors are being deployed across multiple functional domains, and each application creates a different demand profile. Keyless entry systems remain a major driver, reflecting the broader industry movement toward seamless access and digital key ecosystems. Power door systems introduce additional requirements for reliable detection, actuation coordination, and failure-mode resilience. Gesture control systems represent a more advanced interaction layer, particularly relevant where interior and exterior interfaces are being redesigned to support touchless operation and intuitive user experiences.
Automotive Door Handle Sensors Market
These application categories do not grow in isolation. Their adoption patterns are influenced by vehicle segment strategy, regional consumer preferences, electrification roadmaps, and the pace at which OEMs are willing to standardize new interaction models. The report analyzes how these forces interact, enabling readers to gauge which application areas are likely to generate the most consistent demand and which may remain more niche or region-specific over the forecast window.
Competitive Dynamics and the Shape of Market Leadership
The industry is shaped by a group of established players with distinct technical strengths and integration philosophies. NXP Semiconductors brings automotive NFC door handle reference designs and solutions optimized for compact integration. Melexis contributes Hall effect and low-power sensor solutions, including door handle wake-up switches and e-door handle applications. Continental AG has developed capacitive door handle sensor modules with features such as gesture recognition and enhanced false-trigger resistance. Valeo SA supplies ultrasonic-based flush handle sensor systems for hands-free activation across luxury and mass-market vehicles. Infineon Technologies supports door handle detection and control through microcontrollers and sensor ICs for proximity and position sensing. NMB Technologies Corporation manufactures vehicle door handle systems with integrated sensor solutions for OEM customization, including sensing and lighting. ADAC Companies provides vehicle access systems with integrated sensing technologies, capacitive sensors, and microswitches in exterior door handles and trim.
Taken together, these participants illustrate a competitive environment where differentiation is increasingly tied to integration quality, reliability, and the ability to meet OEM-specific design requirements. The report further examines market concentration indicators to provide a clearer picture of how consolidated the field is and where new entrants or niche solutions may still find room to compete.
Regulation, Safety, and the New Compliance Imperative
Regulatory developments are becoming a decisive factor in product planning. In January 2026, China’s Ministry of Industry and Information Technology approved the mandatory national standard GB 48001-2026, Safety Technical Requirements for Automotive Door Handles. The standard addresses safety concerns associated with hidden or flush door handle designs, particularly in electrified vehicle architectures. New vehicle type approvals must comply fully from January 1, 2027, with a transition period extending to January 1, 2029 for previously approved vehicles. This regulatory move reflects a broader scrutiny of electronic door release reliability and signals that safety performance will be a major engineering and procurement consideration in the near term.
At the same time, investigative coverage in the United States has drawn attention to potential defects in electronic door releases in certain Tesla models, with reports of occupants trapped and fatalities linked to crashes where doors would not open. While each case involves specific technical and legal contexts, the cumulative effect is clear: consumer safety, fail-safe design, and verifiable reliability are moving to the foreground of automotive access-system discussions. These dynamics create both risk and opportunity. Suppliers that can demonstrate robust safety performance, transparent validation, and compliance readiness may gain a meaningful advantage in OEM evaluations.
Recent Developments That Are Already Shaping Procurement and Roadmaps
The report incorporates recent events that are actively influencing market direction. In January 2026, both regulatory approval activity and high-profile safety investigations reinforced the importance of dependable door handle sensing and release mechanisms. Then, in February 2026, Continental AG introduced a new capacitive door handle sensor module featuring integrated gesture recognition and improved false-trigger resistance for premium EV platforms. This launch highlights the accelerating focus on user experience, false-trigger mitigation, and electrification-aligned design. Such developments are not isolated news items; they are indicators of how product roadmaps, qualification processes, and buying criteria are shifting in real time.
Automotive Door Handles Market
How to Use This Research for 2026 Decision-Making
The strategic value of the full study lies in its ability to convert market signals into executable insight. The report is intended to support several concrete decisions, including:
- Portfolio prioritization: Determining which sensor technologies and application segments deserve the greatest engineering and commercial focus in the coming years.
- Regional planning: Aligning supply, localization, and market-entry strategies with region-specific demand patterns and regulatory timelines.
- Competitive benchmarking: Understanding where leading suppliers are concentrating their capabilities and where differentiation opportunities remain.
- Risk management: Anticipating safety-related compliance requirements and integrating them into product validation and procurement strategies.
- Investment and partnership decisions: Identifying where long-term market growth is most credible and which capability gaps may create collaboration or acquisition opportunities.
Completing the Picture: Accessing the Full Market Intelligence
This article provides a structured overview of the themes, growth path, and competitive context that define the Automotive Door Handle Sensors Market. However, the full report contains the detailed sizing framework, segmentation comparisons, regional breakdowns, competitive profiles, and operational guidance needed to turn these themes into precise strategic actions. For teams planning product launches, capacity decisions, supplier negotiations, or market-entry assessments in 2026, the complete dataset and analytical commentary offer the depth required to reduce uncertainty and support confident choices.
To access the full market research and obtain the complete segmentation detail, regional analysis, and company-level intelligence, visit the official report page. The complete study is designed to serve as a working reference for strategic planning throughout the forecast period and beyond.
For detailed analysis of this topic, please visit the official page: Automotive Door Handle Sensors Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Global Wood Pallet Market to Reach $19.99 Billion by 2032 at 4.58% CAGR
By PW Consulting, 2026-09-16
Strategic Intelligence for the Wood Pallet Market: Navigating Growth and Complexity in 2026 and Beyond
The global supply chain ecosystem relies heavily on the humble yet critical wood pallet. As we move through 2026, industry stakeholders face a landscape defined by steady expansion, regulatory evolution, and intense competitive consolidation. PW Consulting is proud to introduce our latest comprehensive market research on the Wood Pallet Market, a study designed to equip decision-makers with the foresight needed to thrive in a maturing industry. This report serves as more than a static snapshot; it is a dynamic strategic tool built to clarify investment paths, operational risks, and long-term growth opportunities across the forecast horizon.
Wood Pallets Boxes Packaging Market
Our analysis covers the historical trajectory from 2020 through 2025 and projects performance through 2032. The overarching story is one of reliable, compounded growth. The market has demonstrated consistent revenue expansion over the past half-decade, reaching a valuation of approximately 14.61 billion USD in 2025. Looking ahead, the forecast period indicates a continued upward trend, with the market expected to grow to 14.91 billion USD in 2026 and further accelerate toward a 19.99 billion USD valuation by 2032. This trajectory is underpinned by a forecasted CAGR of 4.58 percent, signaling a healthy demand environment driven by foundational logistics needs and evolving supply chain configurations. Such macroeconomic indicators provide the baseline for strategic planning, yet understanding the nuances behind the aggregate numbers is where true competitive advantage lies.
Navigating the Competitive Arena
The market structure reveals a landscape dotted with both dominant integrated players and specialized niche operators. Concentration metrics indicate that the top three competitors hold 42.0 percent of the market share, while the top five entities command 55.0 percent. This level of concentration suggests that while scale advantages are significant, there remains substantial room for specialized providers to capture value through customization, service quality, and regional expertise.
Leading the charge among major manufacturers is PalletOne Inc., based in Bartow, Florida. As the largest new wood pallet manufacturer in the United States, PalletOne offers a comprehensive suite of services spanning lumber sourcing to finished products, including new and recycled pallets, custom crates, and repair services. A recent development underscores the aggressive consolidation shaping the sector: in April 2026, UFP Industries acquired John Rock to expand PalletOne's footprint in the northeast. This move highlights a strategic push to deepen regional density and logistical efficiency, a trend that enterprises must monitor closely when evaluating supplier stability and market entry barriers.
On the other side of the operational spectrum, Millwood Inc. exemplifies the scale of processing and distribution. With an annual throughput of 200 million pallets, Millwood supplies new and recycled pallets to national accounts, leveraging over 40 years of engineering and manufacturing experience. Such scale allows for significant cost efficiencies and reliability, making it a critical benchmark for assessing operational standards in the industry.
International players are also redefining the competitive boundaries. Falkenhahn AG continues to innovate within the EPAL and wooden pallet solutions space, while PGS Group in France provides standard and custom wooden pallets and packaging solutions, emphasizing versatility in European markets. Meanwhile, Challenger Pallet focuses on sustainability-driven offerings, including custom and heat-treated pallets, alongside repaired and remanufactured options. Their commitment to new tree planting partnerships reflects a broader industry shift toward environmental stewardship that is increasingly influencing procurement criteria.
Regional specialization remains a potent strategy. Wooden Pallets LTD, operating out of Silsbee, Texas, produces over 15,000 pallets daily across facilities in Texas and Louisiana, demonstrating the enduring importance of localized production to meet demand fluctuations. Troymill Wood Products in Ohio serves the wholesale pallet and lumber market with a strong emphasis on compliance, offering in-house heat-treated pallets that meet ISPM-15 standards for export shipments. Similarly, Kamps Pallets distinguishes itself through enterprise-wide sustainability initiatives, including Zero Waste Certification, highlighting how environmental credentials are becoming a core component of brand value and operational efficiency.
Regulatory and Sustainability Dynamics
The strategic landscape for 2026 is heavily influenced by a complex web of regulations and sustainability imperatives. Compliance is no longer merely a checkbox; it is a market access requirement and a driver of innovation. A pivotal regulatory development is the entry into force of the EU Deforestation Regulation (EUDR). For large companies, compliance is required by December 30, 2025, with small companies following by June 30, 2026. New pallets, classified under HS code 4415, now require a due diligence statement proving deforestation-free origin. This regulation introduces new layers of traceability and documentation that will reshape sourcing strategies and cross-border trade flows.
Simultaneously, ISPM-15 compliance remains mandatory for export pallets. Manufacturers and exporters must ensure that wooden pallets are heat-treated and stamped to meet international phytosanitary requirements. Companies like Troymill Wood Products have built their value proposition around this compliance, offering in-house treatment capabilities that streamline the export process. As global trade volumes recover and reconfigure, the ability to navigate phytosanitary standards efficiently becomes a critical differentiator for logistics providers and pallet suppliers alike.
Advocacy and industry collaboration are yielding tangible results. In May 2026, the National Wooden Pallet and Container Association secured a significant victory by obtaining an exclusion for wooden pallets from California's new Extended Producer Responsibility (EPR) scheme. This outcome demonstrates the power of collective industry action in shaping regulatory frameworks to ensure that wood pallets, which are inherently reusable and recyclable, are not unfairly burdened by waste management policies designed for other materials. Furthermore, in February 2025, the Pallet Foundation awarded a historic grant to the National Wooden Pallet and Container Association to advance U.S. softwoods research. This investment in material science underscores the industry's commitment to optimizing raw material utilization and enhancing performance characteristics.
Segmentation and Structural Insights
Understanding the structural composition of the market is essential for targeted strategy. While specific regional and application breakdowns are detailed in the full report, the broader segmentation patterns reveal clear areas of focus. The market is divided across distinct product types, including softwood pallets, hardwood pallets, and a growing segment of recycled and engineered wood pallets. Each category presents unique value propositions, cost structures, and application suitability.
Softwood continues to dominate as a raw material backbone. Historical data indicates that softwood lumber accounted for a substantial majority of the lumber used in U.S. wooden pallet and container production. This reliance reinforces the importance of sustainable forestry management and supply chain resilience for softwood suppliers. In terms of dimensions, the 48 x 40 pallet size held a dominant new pallet market share historically, reflecting standardization benefits and compatibility with existing logistics infrastructure. However, the demand for custom sizes and specialized configurations persists in specific industrial and manufacturing contexts.
The application landscape spans diverse sectors, including logistics and transportation, manufacturing, retail and e-commerce, food and beverages, and other specialized uses. Each vertical imposes distinct requirements regarding durability, hygiene, load capacity, and handling cycles. For example, the retail and e-commerce segment often demands high volumes of standardized pallets to support rapid distribution, while manufacturing may require tailored solutions for specific machinery or production line constraints. The report delves deeply into these application dynamics, helping clients identify high-growth niches and understand the competitive intensity within each segment.
Operational Resilience and Waste Management
Sustainability metrics and waste management data provide critical context for the circular economy narrative. Contrary to perceptions of high waste generation, industry data reveals that only a small fraction of wood landfilled by municipal solid waste landfills and construction and demolition landfills consists of wood pallets. This statistic speaks to the high recovery, reuse, and recycling rates inherent in the pallet ecosystem. Companies with robust repair and remanufacturing capabilities, such as Challenger Pallet and Kamps Pallets, are well-positioned to capitalize on these circular flows, reducing material costs and enhancing environmental profiles. The shift toward recycled and engineered wood pallets is not just a sustainability trend; it is an economic opportunity to leverage alternative material streams and extend asset lifecycles.
Why This Report is Essential for 2026 Decision-Making
The Wood Pallet Market research from PW Consulting is designed to translate these complex dynamics into actionable intelligence. The report provides a granular examination of market size, growth trajectories, and segmentation structures that enable precise market sizing and forecasting for corporate planning teams. Beyond the numbers, we analyze the competitive profiles of key players, their strategic moves, and the implications of recent developments such as the UFP Industries acquisitions and the regulatory victories by industry associations.
Wood Pallet Market
Stakeholders will gain access to detailed assessments of regulatory risks, including the implications of EUDR and ISPM-15, along with guidance on compliance pathways. The study also explores raw material dynamics, regional demand drivers, and the evolving role of sustainability in procurement decisions. By mapping the competitive concentration and identifying the strategic positioning of leaders like PalletOne, Millwood, Falkenhahn, and others, the report offers a clear view of the barriers to entry, partnership opportunities, and potential threats.
We invite industry executives, investors, and supply chain leaders to leverage this comprehensive intelligence to sharpen their strategic focus. The full report contains the complete segmentation data, deep-dive regional analysis, detailed company profiles, and comprehensive forecasts that are essential for making informed decisions in 2026 and preparing for the years ahead. Access the full market research to unlock the detailed insights and secure a competitive edge in the evolving wood pallet landscape.
For detailed analysis of this topic, please visit the official page: Wood Pallet Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Attapulgite Market Worth USD 300M in 2025, Projected 2.8% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence for the Attapulgite Market 2026–2032: Navigating a Steadily Expanding Commodity Landscape
Decision-makers across industrial manufacturing, energy, agriculture, and life sciences operate in an environment where raw material availability, regulatory stringency, and supply chain traceability increasingly determine competitive positioning. Attapulgite clay has evolved far beyond its traditional role as a functional mineral additive. Today it sits at the intersection of performance rheology control, high-efficiency absorption, and specialized formulation requirements that demand consistent purity, documented sourcing, and application-tailored processing. Understanding where this market is headed, which structural forces will shape pricing and capacity, and how established players are adapting to new compliance and performance benchmarks is no longer optional for procurement leaders, product developers, and corporate strategists. Our latest Attapulgite Market research study translates multi-year historical tracking, forward-looking forecasting, and granular competitive observation into an operating intelligence resource designed for 2026 planning cycles.
Why This Study Matters for 2026 Decision-Making
The attapulgite sector does not experience dramatic cyclical spikes; it advances through structural demand shifts, formulation engineering, and incremental capacity adjustments. That characteristic makes it a market where strategic misreads can quietly erode margins, delay product launches, or weaken supply resilience over several years. The research anchors its analysis in a documented historical trajectory from 2020 through 2025, then extends its projection horizon across 2026–2032. Over this multi-year arc, the industry reflects a measured but persistent expansion, supported by steady CAGR movement and a market valuation that has progressed from a 2020 baseline around 250 million USD to a 2025 positioning near 300 million USD, with the forecast window tracking continued growth as formulation adoption broadens and regional supply networks mature. Rather than treating these figures as isolated numbers, the study frames them as symptoms of deeper dynamics: application-specific performance requirements, evolving grade differentiation, and operational decisions about sourcing, quality control, and regional distribution. For strategic teams, this framing provides a practical foundation for scenario planning, capacity evaluation, vendor qualification, and portfolio prioritization.
Market Structure: Types, Applications, and the Meaning of Segmentation
Attapulgite’s commercial profile is shaped by how the mineral is processed and where it is deployed. On the type dimension, the market splits between colloidal-grade material engineered for rheology modification, suspension stability, and fine dispersion, and sorptive-grade material optimized for absorption, filtration support, and containment functions. These two streams do not merely represent different particle characteristics; they correspond to distinct formulation needs, processing tolerances, and performance validation pathways. In the application landscape, multiple verticals draw on attapulgite for different technical outcomes. Oil and gas operations leverage it for drilling fluid performance and controlled fluid loss. Pet waste absorbents depend on its high-capacity containment behavior for consumer and institutional hygiene products. Agriculture utilizes it for soil conditioning, carrier functionality, and moisture-related formulations. Paints and coatings apply it to control viscosity, suspension, and sag resistance. Medical and pharmaceutical uses require refined, traceable grades aligned with strict quality expectations.
Attapulgite Market
The strategic implication for enterprises is that demand for attapulgite cannot be treated as a single pool. A product team developing a coating system faces a different value proposition than a procurement group sourcing absorbent media or a formulation scientist qualifying a pharmaceutical excipient. The research examines these demand channels through the lens of performance requirements, regulatory exposure, substitution risk, and regional supply readiness, allowing readers to see which application areas are most sensitive to quality consistency, which are more influenced by cost structure, and which are likely to absorb the market’s incremental growth over the forecast window. Detailed segmentation data, regional breakdowns, and type-specific sizing are reserved for the full report so that strategy teams can pressure-test assumptions rather than rely on summary approximations.
Competitive Dynamics: Who Shapes the Market and How
Attapulgite is a concentrated industry. The top three players command roughly two-thirds of market share, while the leading five collectively hold around 80 percent, a structure that shapes pricing behavior, capacity investment patterns, and the bargaining power of downstream buyers. At the center of this landscape are companies that have built reputations on consistent grade quality, application engineering support, and increasingly, documented traceability and compliance readiness. Active Minerals International LLC operates from Houston, Texas, and supplies gel-quality attapulgite clays, including Acti-Gel and Min-U-Gel families, for rheology modification, suspension, and absorption applications. Oil-Dri Corporation of America, based in Chicago, Illinois, provides attapulgite clay as a functional absorbent and rheology modifier across industrial, pet care, and drilling-related uses. Clariant AG, headquartered in Muttenz, Switzerland, delivers colloidal attapulgite clay for pharmaceutical, cosmetic, and specialty absorbent applications, with a product posture that increasingly emphasizes refined performance and regulated-grade readiness. BASF SE, located in Ludwigshafen, Germany, offers attapulgite-based products for coatings, adhesives, and industrial rheology modification, reinforcing the mineral’s role in formulation science rather than commodity distribution alone.
Operational Intelligence Built Into the Report
A market of this structure requires more than aggregate sizing. The study is built as a decision-support instrument, combining historical trend reconstruction with forward modeling and competitive observation. Readers receive a calibrated view of how the market moved through 2020–2025 and how momentum is expected to evolve through 2032 under multiple demand and supply scenarios. The report examines type-based distinctions between colloidal and sorptive grades, including the engineering rationale that drives selection, the performance thresholds that influence qualification, and the price-quality-performance trade-offs that procurement and R&D teams must manage. Application-level analysis traces where attapulgite delivers differentiated value, how substitution risk varies by end use, and which verticals are most exposed to regulatory or formulation-driven shifts in demand. Regional dynamics are treated with attention to supply availability, logistics complexity, and local manufacturing or specification requirements, enabling readers to assess where sourcing resilience matters most.
Rather than presenting segmentation as isolated numbers, the study connects each dimension to procurement logic, product development implications, and supply chain planning. It also tracks capacity posture, grade specialization, and the ways incumbents are responding to performance expectations and compliance norms. This integrated approach allows teams to interpret headline market direction in the context of segment-specific behavior, which is essential when allocation, qualification, and supplier selection decisions have long payback periods and high switching costs.
Recent Developments That Reset the Competitive Baseline
Two recent events illustrate how quickly the strategic environment can shift. In December 2025, Clariant launched Pharmasorb™ Colloidal attapulgite clay, a highly refined pulverized grade designed for cosmetic and pharmaceutical applications under cGMP guidelines. This launch signals more than a product release; it reflects a broader industry movement toward documented quality systems, controlled impurity profiles, and formulation-specific validation. For downstream manufacturers in life sciences and personal care, the availability of cGMP-aligned attapulgite changes supplier qualification criteria, audit expectations, and the cost of compliance. For competitors, it raises the bar on what constitutes a premium grade and how specialized processing is positioned in the market.
Worldwide Pharmaceutical Grade Bentonite Powder Market
Earlier in October 2025, Active Minerals International LLC announced a supply partnership with the RBH Group to provide reliable, traceable high-performance attapulgite clay supply chains for European and Asian manufacturers. This collaboration highlights the growing importance of traceability, regional supply reliability, and multi-market coordination. For buyers in Europe and Asia, it suggests a market response to the risk of fragmented sourcing and inconsistent grade quality. For strategists, it underscores that attapulgite is increasingly managed as a performance-critical input rather than a generic bulk material, and that supply relationships are being structured around documentation, continuity, and specification adherence as much as price.
These developments sit within wider industry context. US fuller's earth, primarily attapulgite, accounts for a dominant share of the absorbents segment according to USGS estimates, reinforcing the mineral’s centrality in absorption applications. At the same time, USGS Mineral Commodity Summaries and production tracking indicate that fuller's earth production and consumption data for 2025 remain central reference points for understanding supply behavior, even as unit value reporting trends toward aggregated ex-works presentation rather than separately disclosed annual pricing. For companies operating in or adjacent to this market, the implication is clear: operational decisions should factor in both performance differentiation and the reality that public price signals can lag the more granular dynamics that shape procurement negotiations and grade selection.
Reading the Market Through a Strategic Lens
The attapulgite market rewards organizations that treat it as a performance ecosystem rather than a uniform commodity. Grade selection affects viscosity control, suspension stability, absorption capacity, and regulatory readiness. Application context determines whether the critical variable is cost efficiency, purity documentation, batch consistency, or functional performance. Regional sourcing influences lead times, specification alignment, and resilience to supply interruptions. Competitive concentration means that supplier relationships, qualification status, and long-term capacity access can be as important as short-term price movements. In that environment, strategy teams need intelligence that links demand direction to grade economics, application requirements, and supplier behavior, while also accounting for compliance shifts and the increasing premium on traceability.
The study therefore emphasizes practical interpretation over simple aggregation. It helps readers distinguish between markets where demand is being driven by formulation performance, those where absorption needs dominate, and those where regulatory or specification requirements are reshaping supplier selection. It also illuminates the way incumbents are using product specialization, supply partnerships, and compliance-oriented differentiation to protect position and expand value capture. For 2026 planning, this means organizations can better assess whether they are exposed to grade-quality risk, whether their sourcing strategy aligns with regional supply realities, and whether their product roadmaps are aligned with the types of attapulgite applications that are most likely to absorb incremental market growth.
What the Full Study Delivers for Your Team
- A documented historical baseline and multi-year forecast that contextualizes current market size and forward momentum without relying on isolated snapshots.
- Type-based analysis that explains how colloidal and sorptive grades differ in performance logic, application fit, and procurement implications.
- Application-level interpretation across oil and gas, pet waste absorbents, agriculture, paints and coatings, and medical and pharmaceutical uses, with attention to performance drivers, substitution risk, and specification sensitivity.
- Competitive profiling of key players, including their positioning, grade focus, application emphasis, and recent strategic moves that affect supply reliability and premium-grade availability.
- Supply chain and regulatory context, including traceability expectations, compliance-aligned product launches, and industry data references that shape sourcing and qualification decisions.
- Decision-ready framing for procurement, R&D, capacity planning, and regional sourcing strategy, enabling teams to connect market direction to operational choices.
Detailed segmentation values, regional figures, and type-specific market splits are presented in full within the complete study so that planning teams can work from precise inputs rather than rounded estimates. The objective is not to publish a static table but to equip decision-makers with context, interpretation, and a verifiable evidence base for evaluating suppliers, prioritizing applications, and aligning product and sourcing strategies with the structural direction of the attapulgite market.
How to Use This Intelligence for 2026 Planning
Senior teams can translate the study’s direction into several concrete actions. Procurement leaders can benchmark supplier eligibility against grade specialization, traceability expectations, and regional supply continuity rather than price alone. R&D and formulation teams can map application requirements to the type of attapulgite most likely to deliver performance consistency and reduce downstream qualification friction. Strategy and corporate development groups can evaluate where demand is structurally strengthening, which segments are sensitive to compliance or specification shifts, and how competitive concentration may shape supplier access over time. Operations and supply chain teams can use the report’s dynamics to stress-test sourcing plans against regional variability, documentation requirements, and the likelihood that premium-grade supply becomes more differentiated over the forecast window.
The market’s measured expansion, combined with rising expectations for quality consistency, traceability, and application-specific performance, makes disciplined intelligence especially valuable. Organizations that read attapulgite only through total market size risk missing the grade, application, and regional distinctions that actually govern cost, performance, and supply resilience. Those that incorporate segmentation logic, competitive behavior, and compliance-driven product evolution into their planning are better positioned to protect margins, qualify suppliers efficiently, and align product roadmaps with durable demand channels.
Accessing the Complete Market Intelligence
This overview establishes the strategic frame for the full Attapulgite Market research study: the scale of historical movement, the shape of the forecast window, the concentration of competition, the significance of recent product and supply-chain developments, and the operational questions that matter most for 2026 planning. The complete study extends this foundation with precise segmentation data, comprehensive company profiles, deeper application and type analysis, and regional context designed to support procurement, formulation, sourcing, and portfolio decisions. To read the full dataset and use the complete segmentation, competitive, and dynamics sections in your planning work, access the full report at the source webpage, where the detailed figures, tables, and supporting analysis are available for direct review and internal distribution.
For detailed analysis of this topic, please visit the official page: Attapulgite Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
Strategic Intelligence Brief: 2-Hydroxyethyl Methacrylate Market Outlook 2026–2032
The global chemical landscape is undergoing a structural recalibration. For industry leaders operating in specialty monomers, the window for strategic positioning is narrowing as regulatory frameworks tighten and downstream applications demand ever-higher material performance. Our latest market research study on 2-Hydroxyethyl Methacrylate (HEMA) delivers a comprehensive, data-grounded assessment of how this critical building block will evolve through 2032—and what it means for procurement, R&D, and competitive strategy in 2026 and beyond.
This briefing preview synthesises the foundational findings of the full report. It is designed to demonstrate analytical rigor, map the terrain of critical decision variables, and illustrate why a deeper, segmented intelligence package is indispensable for executives navigating the next investment and sourcing cycles. Core numerical breakdowns by region, purity tier, and end-use vertical are intentionally held back; they are available in their complete, modelled form within the published study.
Macro Trajectory: A Market in Steady Expansion
Historical reconstructions from 2020 through 2025 reveal consistent top-line growth for HEMA, with global revenue climbing from approximately 432.19 million USD to a recent base-year level of 531.0 million USD. The momentum does not plateau. Our forecast horizon extends through 2032, projecting a continued upward arc that carries the market past the 700-million-dollar threshold by the close of the period. The compound annual growth rate across this forecast window is modelled at 4.2 percent, a figure that reflects resilient demand across established application sectors and emerging high-value segments.
Several structural forces underpin this trajectory. The shift toward electric mobility has intensified requirements for advanced thermal-management coatings and protective resin systems. Biomedical and dental material innovation continues to drive demand for ultra-high-purity grades that meet stringent regulatory and biocompatibility thresholds. Simultaneously, optical clarity requirements in consumer and medical hydrogels, along with specialty adhesive formulations, create incremental pull from purity-sensitive applications. These demand vectors are not evenly distributed; they concentrate value in specific purity windows and regional supply nodes, a dynamic that is unpacked in granular detail in the full study.
The Purity Paradigm: How Specification Drives Commercial Value
Not all HEMA is commercially equivalent. Purity thresholds act as powerful pricing and demand filters, and the market has bifurcated around three dominant specification tiers. Producers and buyers alike must understand where value accrues, where margin pressure exists, and how technical requirements translate into procurement premiums.
High-purity grades command particular attention in sectors where impurity profiles directly affect end-product performance. Biomedical, pharmaceutical, and optical applications mandate rigorous distillation, repeated testing, and adherence to ISO-aligned quality protocols for material designated at or above 99 percent purity. These specifications are not optional extras; they are preconditions for market entry in regulated verticals. Slightly lower purity bands still hold substantial commercial relevance, particularly in coatings and reactive resin formulations where cost-performance balances differ. The full report maps exactly how each purity tier contributes to value creation and identifies which downstream customers are willing to pay for specification upgrades versus those optimising on grade cost.
Application Segmentation: Where Demand Is Concentrated
HEMA flows into a diverse but unevenly weighted set of end markets. Coatings represent a major consumption hub, leveraging the monomer’s contributions to gloss, adhesion, and film integrity. Reactive resins form another substantial pillar, particularly where cross-linking behaviour and interfacial compatibility matter. Adhesives capture a meaningful share, benefiting from HEMA’s ability to fine-tune tack, flexibility, and bond durability. A residual category encompasses specialised and niche deployment scenarios that, while individually smaller, collectively represent innovation frontiers.
The strategic significance of this segmentation lies in its asymmetry. A relatively small shift in specification requirements within a high-value application can disproportionately impact overall margin profiles. Likewise, regional demand patterns differ markedly, shaped by local manufacturing intensity, regulatory stance, and the maturity of downstream processing clusters. Our analysis isolates the precise contribution of each application vertical and each geography, but the full breakdown—with scenario-tested sensitivities—is reserved for the complete intelligence package.
Competitive Landscape: Capability, Geography, and Moves
The HEMA market is characterised by a moderately concentrated supplier base, with a limited number of players controlling a substantial share of throughput. Competitive positioning depends on a combination of manufacturing footprint, purity capability, application-specific technical support, and responsiveness to regulatory shifts.
2-Hydroxyethyl Methacrylate Market
2-Ethylhexyl Methacrylate (2-EHMA) Market
Several active participants illustrate the current market architecture. Shakti Chemicals, headquartered in Mumbai, operates as a trader and supplier supporting polymer chemistry applications across Asia, emphasising regional distribution reach. Qingdao RENAS Polymer Material Co., Ltd., based in Qingdao, China, focuses on HEMA as part of a broader specialty chemicals and polymer materials portfolio. Nantong Chem-land Co., Ltd., also in China, supplies high-purity grades for industrial and specialty use, aligning product range with specification-sensitive buyers. Yancheng Green Chemicals Co., Ltd., likewise situated in China, manufactures HEMA for polymer synthesis and advanced chemical applications, reinforcing the country’s role as a production anchor.
Beyond these named participants, the competitive field includes larger diversified chemical firms that deploy HEMA in more complex value chains. Recent activity underscores how innovation and compliance shape the battlefield. In mid-2025, Chemical United introduced HEMA HISS, an ultra-pure 99.5 percent grade engineered for high-clarity applications spanning soft contact lenses, 3D-print resins, medical hydrogels, and high-gloss formulations. This launch signals intensifying competition at the premium purity end and the growing importance of application-tailored product architecture.
In October 2024, Dow collaborated with an automotive manufacturer on a new HEMA-based coating for electric vehicle batteries, with demonstrated improvements in thermal management and battery-life extension. Such application-led co-development points toward a future where monomer value is co-created with downstream partners rather than sold as a commodity specification. In January 2024, Evonik launched VISIOMER HEMA-P 100, a phosphate methacrylate monomer derived from HEMA, aimed at enhancing flame retardancy, adhesion, and corrosion resistance in coatings and composites. This type of derivative innovation expands the functional envelope of HEMA chemistry and creates adjacent opportunity spaces.
Regulatory and Environmental Constraints as Strategic Variables
Regulation is no longer a background condition; it is a direct driver of market structure. The EU Cosmetics Regulation (EC 1223/2009) restricts HEMA in nail cosmetics to professional use only, mandating specific labelling and barring non-compliant products from market entry since September 2021. In contrast, the United States continues to permit HEMA in dental adhesives, medical tapes, and wound dressings without equivalent professional-use limitations, preserving broader access for medical and dental applications. This transatlantic divergence creates distinct compliance pathways and affects how multinational suppliers design portfolio strategies for Western markets.
Environmental and safety considerations further embed operational constraints. HEMA is hydrolysed to methacrylic acid and ethylene glycol, and producers are expected to monitor and treat effluent to limit release to roughly 0.02 tonnes per year per plant. These abatement expectations shape capital planning and regional siting decisions. Meanwhile, upstream feedstock exposure remains significant: HEMA production depends on ethylene glycol, with prices exhibiting high volatility linked to crude oil and natural gas cycles. Margin management therefore requires forward-looking procurement strategies and, where feasible, integration or hedging mechanisms that reduce exposure to energy-linked input swings. ISO standards for high-purity grades (99 percent and above) add another compliance layer, mandating rigorous distillation and testing protocols for biomedical and pharmaceutical applications.
Why 2026 Calls for Decision-Ready Intelligence
The coming year will test companies on multiple fronts at once. Feedstock volatility will continue to complicate cost forecasting. Regulatory divergence will force region-specific packaging, labelling, and distribution decisions. Premium-purity demand will accelerate where biomedical, optical, and high-performance coatings converge. At the same time, capital allocation decisions on capacity, purification capability, and technical service infrastructure must be made with a view toward 2032, not merely the next quarter.
Executives need more than headline numbers. They require a decision architecture that connects macro trajectory to segment-level economics, maps competitive capability to application opportunity, and quantifies how regulatory and environmental constraints alter viable market access. The full report is built for exactly this purpose.
What the Full Study Delivers
Beyond the macro arcs and competitive snapshots previewed here, the complete market research package provides:
- A fully segmented revenue model by region, purity tier, and application, capturing both current sizing and forecast evolution through 2032 without exposing sensitive breakdowns until accessed in full.
- Scenario-tested sensitivity analysis around feedstock price volatility, enabling procurement and finance teams to stress-test margin assumptions under alternative energy-price pathways.
- A detailed regulatory matrix covering EU cosmetics restrictions, US medical and dental permissions, environmental effluent expectations, and ISO-grade quality protocols, with implications mapped to product strategy and market entry.
- Company-level profiles and recent development tracking for active market participants, including product launches, application co-development, and derivative innovation that signal where competitive advantage is being built.
- Strategic recommendations aligned to sourcing, capacity planning, specification upgrades, and regional compliance positioning, calibrated to different organisational roles from R&D to commercial leadership.
The complete dataset, including region-by-region and application-by-application contributions along with the precise revenue figures underpinning each segment, is available in the published report. Accessing the full study provides the granular intelligence required to translate market direction into concrete commercial and operational decisions.
Conclusion: Position Now or Pay Later
The HEMA market is expanding, but growth is uneven and increasingly governed by specification, compliance, and application-specific performance requirements. A 4.2 percent compound annual growth rate through 2032 is meaningful, yet the real strategic question is not how large the market becomes—it is which segments, which purity tiers, and which geographies will capture disproportionate value. Companies that act in 2026 with precise, segment-aware intelligence will be better placed to secure feedstock resilience, align product portfolios with regulatory realities, and capture premium demand where performance thresholds create pricing power.
This briefing has outlined the terrain. The full report delivers the detailed map. For procurement leaders, R&D strategists, and commercial executives, the study provides the decision-grade foundation needed to move from awareness to action before the window narrows further.
For detailed analysis of this topic, please visit the official page: 2-Hydroxyethyl Methacrylate Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting Forecast: Niobium Carbide Market Hits $58.9M in 2025, Growing at 5.1% CAGR to 2032
By PW Consulting, 2026-09-16
Strategic Intelligence Report: Navigating the Niobium Carbide Market Landscapes in 2026
As industries pivot toward advanced materials that offer superior hardness, thermal stability, and chemical resistance, Niobium Carbide (NbC) has emerged as a critical component in high-performance manufacturing. For strategic planners, investors, and procurement leaders, understanding the trajectory of this market is no longer optional—it is a necessity for maintaining competitive advantage. PW Consulting presents our latest comprehensive analysis, designed to equip decision-makers with the actionable intelligence required to navigate the complexities of the Niobium Carbide Market between 2026 and 2032.
Market Trajectory and Economic Outlook
The global Niobium Carbide Market is demonstrating steady resilience, characterized by consistent growth driven by demand in aerospace, defense, and cutting tool industries. Our analysis, grounded in historical data from 2020 through 2025, projects a robust forecast period extending to 2032. The market has evolved from a valuation of approximately 46.5 million USD in 2020 to an anticipated 58.9 million USD in the base year of 2025.
Looking forward, the market is expected to reach 62.43 million USD in 2026, climbing steadily toward 83.69 million USD by 2032. This growth trajectory reflects a Compound Annual Growth Rate (CAGR) of 5.1 percent over the forecast period. Such stability suggests that while the market is niche, it is insulated from volatile shocks due to the essential nature of niobium carbide in critical applications. However, revenue projections are only the surface layer of our findings. The real value lies in understanding the drivers behind these numbers and the specific segments poised for accelerated expansion.
Structural Segmentation and Material Specifications
The market is not monolithic. It is differentiated by purity levels, physical forms, and application verticals, each carrying distinct margin profiles and supply chain requirements. Our report dissects these segments to reveal where value is being created and where commoditization risks exist.
Purity and Form Factors
Purity remains a primary differentiator in the Niobium Carbide Market. The segmentation spans from 2N purity levels to 5N high-purity grades. Higher purity grades, such as 5N Niobium Carbide, cater to specialized sectors including aerospace and defense, where impurity levels must be minimized to ensure material integrity under extreme conditions. Conversely, lower purity grades find utility in bulk metallurgical applications and carbide alloys where cost efficiency is prioritized over extreme performance characteristics.
In terms of physical form, the market is divided into flakes, powder, and sputtering targets. Powder represents a significant portion of the market volume, driven by its versatility in powder metallurgy and coating processes. Sputtering targets are critical for thin-film deposition in electronics and protective coatings, while flakes serve specific industrial manufacturing needs. Understanding the supply dynamics of each form is essential for manufacturers seeking to secure reliable feedstock without compromising on quality specifications.
Application Verticals
The utilization of Niobium Carbide is concentrated across several key application areas. Carbide alloys constitute a major share, leveraging the material's hardness to enhance the durability of hardmetals used in machining. Coating materials represent another vital segment, where NbC is applied to protect components from wear, corrosion, and high-temperature degradation. Other significant applications include cutting and machining tools, which rely on the material's wear resistance to extend tool life, and metallurgical processes where niobium compounds act as grain growth inhibitors or strengthening agents. Each application vertical faces unique regulatory and technical hurdles that influence market entry barriers and pricing power.
Competitive Landscape and Strategic Positioning
The competitive environment is moderately concentrated, with the top five players holding a significant share of the market, while the top three companies account for over half of the total revenue. This concentration indicates a mature market structure where established players dominate supply chains, but there remains room for specialized entrants focusing on high-purity or niche applications.
Key Industry Players
Several global entities define the current competitive landscape. H.C. Starck Tungsten Powders, based in Germany, is recognized for its high-purity NbC and mixed carbide offerings, specifically tailored for cutting tools and cermets with precise grain size control. Their presence underscores the importance of quality consistency in European manufacturing sectors.
Niobium Carbide Market
CBMM, headquartered in Brazil, stands as a primary producer of niobium-based carbides. Their recent launch of a new high-purity NbC powder line specifically for aerospace and defense applications highlights the trend toward specialized material grades in strategic sectors. This move signals a deeper integration of niobium carbide into supply chains requiring certified high-performance materials.
In the Americas, China Molybdenum Co., Ltd. manufactures niobium carbide products tailored for electronics and high-performance applications, linking the material to the broader technology supply chain. NioCorp Developments Ltd., operating out of Nebraska, is advancing integrated processing for niobium compounds, including carbides, as part of their Elk Creek project. This development is particularly significant given the regulatory environment surrounding domestic production.
Additionally, companies such as American Elements, Edgetech Industries LLC, Ottokemi, and Materion Corporation contribute to the diverse supply base. American Elements focuses on high-purity powder with small grain sizes for advanced applications, while Materion Corporation produces advanced materials for aerospace and industrial uses. Ottokemi and Edgetech ensure supply availability from India and the United States respectively, offering high-purity options with international shipping capabilities. These players collectively ensure that supply meets the varied demands of global industries, though geographic diversification remains a strategic priority for many buyers.
Regulatory Dynamics and Supply Chain Risks
A critical component of our 2026 market research is the analysis of the regulatory framework governing Niobium Carbide. The strategic value of this material is amplified by its designation as a critical mineral by the U.S. Government. This designation triggers specific Department of Defense programs aimed at funding domestic exploration and processing projects. For instance, NioCorp Developments' Elk Creek niobium-scandium-titanium project in Nebraska has received attention within these programs as of early 2026, highlighting the intersection of resource security and industrial policy.
Compliance requirements vary significantly by jurisdiction. In Canada, the Export Control List includes niobium carbide under controlled items for strategic applications, necessitating careful adherence to Global Affairs Canada regulations. In the United States, manufacturers producing niobium carbide products for defense or aerospace applications must comply with International Traffic in Arms Regulations (ITAR). Additionally, the Toxic Substances Control Act (TSCA) requires registration of niobium carbide as a chemical substance with the EPA for U.S. manufacturers. These regulatory layers create a compliance burden that acts as a barrier to entry, reinforcing the position of established players who have the infrastructure to manage such requirements.
Worldwide Nb Alloys Market
On the raw material side, niobium oxide serves as the primary feedstock for niobium carbide production. The global production value of niobium supports downstream processing, meaning that any disruption in niobium mining or refining directly impacts carbide availability and pricing. Strategic planners must monitor upstream commodity trends to anticipate cost fluctuations in the carbide market.
Strategic Implications for 2026 Decision Makers
The data and analysis presented in our full report point to several key strategic imperatives for organizations operating in or adjacent to the Niobium Carbide Market in 2026.
- Supply Chain Resilience: Given the regulatory scrutiny and the concentration of supply among top-tier producers, diversifying sourcing channels is essential. Relying on a single region or supplier exposes firms to geopolitical risks and regulatory delays.
- Compliance Investment: With ITAR, TSCA, and export control regulations in play, compliance is not merely a legal formality but a strategic asset. Companies that streamline regulatory adherence can secure contracts in defense and aerospace more effectively than those that lag.
- Purity-Driven Value Capture: As seen in recent product launches by key players, the premium lies in high-purity grades for specialized applications. Manufacturers capable of delivering 5N purity or specialized grain sizes can command better margins than those competing on volume alone.
- Long-Term Planning: The forecast period extends to 2032, indicating a long investment horizon. Capital allocation decisions made in 2026 regarding production capacity or technology adoption will influence market position for the better part of a decade.
Accessing Comprehensive Market Intelligence
While this overview provides a snapshot of market size, key players, and regulatory dynamics, the full depth of our research offers the granular detail required for execution. Our complete market research report delivers a granular breakdown of revenue shares across regions including North America, Europe, Asia Pacific, Latin America, and the Middle East and Africa. It further quantifies the specific market value assigned to each purity level, form factor, and application segment, providing the exact numbers needed for bottom-up forecasting.
Furthermore, the full report includes a detailed competitive benchmarking analysis, assessing the strategic positioning, product portfolios, and recent developments of each key company. It also contains an exhaustive review of regulatory frameworks across multiple jurisdictions, ensuring that your compliance strategy is robust and up-to-date.
For organizations aiming to secure their position in the Niobium Carbide Market, access to this level of detail is indispensable. To download the full report and gain complete access to the segmentation data, historical trends, and forecast models, please visit the PW Consulting research portal. Equip your team with the intelligence needed to navigate 2026 and beyond with confidence.
For detailed analysis of this topic, please visit the official page: Niobium Carbide Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Railcar Leasing Market Hits $187.5M in 2025, Projects 5.5% CAGR to 2032
By PW Consulting, 2026-09-16
Navigating the Rails: Strategic Intelligence for the 2026 Railcar Leasing Market
Setting the Stage for the Next Decade of Growth
The global railcar leasing market stands at a critical inflection point as we move through 2026. Following a trajectory of steady expansion from 2020 through 2025, the industry is positioned to deliver consistent value creation for investors, operators, and logistical partners over the forecast period extending to 2032. This phase of maturation is not merely about volume growth; it is about strategic alignment, regulatory compliance, and the optimization of asset lifecycles in an increasingly complex geopolitical and economic environment.
Our latest market research provides a comprehensive lens through which stakeholders can view these dynamics. The data indicates a robust baseline, with the overall market revenue reaching significant milestones in recent years and continuing to ascend. The forecast period suggests a compound annual growth rate that underscores the resilience of rail transport as a backbone of industrial logistics. For decision-makers, understanding the velocity of this growth is essential for capital allocation, fleet expansion planning, and risk mitigation strategies.
This article serves as a strategic overview of the insights contained within our full report. It highlights the macroeconomic trends, competitive maneuvers, and regulatory frameworks that will define success in this sector. However, to truly capitalize on these insights, leaders need access to the granular segmentation, specific regional valuations, and detailed operational metrics that only the complete study provides.
Market Trajectory and Macroeconomic Indicators
The historical data from 2020 to 2025 reveals a market that has navigated volatility with remarkable stability. After a slight contraction in the early stages of the forecast window, the sector rebounded strongly, culminating in a substantial revenue base by 2025. Looking forward, the projection from 2026 to 2032 outlines a path of sustained upward momentum.
Our analysis forecasts that the market will continue to expand, driven by the increasing demand for efficient freight transport solutions and the modernization of aging fleets. The revenue projections indicate a clear upward trend, suggesting that railcar leasing will remain a vital component of the broader transportation infrastructure. For enterprises planning long-term investments, aligning with this growth trajectory is paramount. The data suggests that those who position their assets and contracts strategically during this window will secure a competitive advantage as the market matures toward the end of the decade.
Understanding the scale of this opportunity is the first step. The total revenue figures projected for the late 2020s and early 2030s represent a significant expansion from the baseline established in the early 2020s. This growth is not uniform; it is fueled by specific operational needs and regional developments that are dissected in depth within our full report. Stakeholders requiring precise valuation models for their portfolios will find the detailed forecasts indispensable for securing financing and justifying expansion initiatives.
Competitive Landscape and Strategic Maneuvers
The competitive environment in railcar leasing is characterized by a mix of established giants and agile regional specialists. Our research profiles key players who are actively shaping the market through acquisitions, partnerships, and fleet modernization. The concentration of market share among top firms remains a critical metric for understanding barriers to entry and potential consolidation opportunities.
In North America, GATX Corporation continues to solidify its position as a premier leasing company. Based in Chicago, GATX offers diverse tank and freight railcar fleets with comprehensive maintenance support. A significant move in early 2026 saw GATX complete the acquisition of a Wells Fargo rail operating lease portfolio, comprising approximately 101,000 railcars. This strategic acquisition nearly doubled its North American lease fleet, signaling a aggressive push to capture market share and expand asset availability in a key region.
Similarly, TrinityRail, headquartered in Dallas, stands as a leading integrated provider with a vast leased railcar inventory supported by manufacturing and logistics services. Their strategy extends beyond leasing into manufacturing and lifecycle management. A notable development in mid-2026 involved TrinityRail Global acquiring a significant stake in a venture with Touax Group and Texmaco Rail & Engineering Ltd. This partnership aims to form India's first global railcar leasing platform, integrating manufacturing, leasing, financing, and lifecycle management. This move highlights a strategic push into emerging markets and vertical integration.
In Europe, the landscape is equally dynamic. VTG Aktiengesellschaft, based in Hamburg, remains Europe's largest private freight wagon leasing operator, offering modal logistics and digital solutions. Beacon Rail Leasing, operating across 18 European countries from the United Kingdom, provides full-service leasing for locomotives and freight wagons. Meanwhile, RAILPOOL GmbH in Munich focuses on electric locomotives and rail vehicles across 19 countries, emphasizing flexible contracts. EUROWAGON Sp. z o.o., based in Warsaw, specializes in modern freight wagons and intermodal solutions across pan-European regions. These companies illustrate the diverse approaches to fleet management and service delivery that define the European sector.
Container Leasing Market
Our report analyzes how these companies interact, compete, and collaborate. It examines the implications of their recent developments on market pricing, availability, and service standards. For clients evaluating potential partners or competitors, these profiles offer a foundational understanding of the strategic priorities driving the industry leaders.
Operational Dynamics and Regulatory Influence
The operational framework of the railcar leasing market is heavily influenced by regulatory environments that vary significantly by region. These regulations impact manufacturing, content sourcing, and leasing transparency, creating both compliance challenges and strategic opportunities for lessors who can adapt quickly.
In the United States, recent implementation of the Freight Car Safety Standards under the Infrastructure Investment and Jobs Act has introduced strict content requirements. Freight cars manufactured on or after December 19, 2025, face limitations on the percentage of content originating from countries of concern or state-owned enterprises. This limit is set to tighten further by December 19, 2028. Manufacturers and lessors must ensure compliance with these content limitation requirements, excluding sensitive technology components. This regulatory shift necessitates a review of supply chains and procurement strategies for any entity operating within the U.S. general railroad system.
Across the Atlantic, the Office of Rail and Road in the United Kingdom has reviewed the competition remedies in the rolling stock leasing market. Their conclusion reaffirms the appropriateness of the Transparency Order, though updates are recommended to align with legislative changes. This ongoing monitoring ensures that the leasing market remains fit for purpose amid broader rail reform efforts. The requirement for transparency continues to shape how leasing terms are negotiated and reported, influencing strategic planning for lessors operating in the UK and European domains.
These regulatory dynamics are not static; they evolve with geopolitical tensions and domestic policy priorities. Our market research integrates these factors into the broader analysis of market dynamics, helping stakeholders anticipate compliance costs and operational adjustments. Understanding the interplay between regulation and lease duration strategies is crucial for maintaining asset utility and legal standing.
Strategic Value for 2026 Decision Makers
Why does this detailed intelligence matter for your organization in 2026? The answer lies in the ability to move from reactive adjustments to proactive strategy. The railcar leasing market is not just about moving goods; it is about optimizing capital intensity, managing risk, and ensuring supply chain reliability.
For investors, the growth trajectory and competitive consolidation suggest a market ripe for strategic capital deployment. Understanding which segments are driving growth allows for targeted investment in fleets that match demand patterns. For operators, knowing the regulatory landscape helps in planning fleet acquisitions that will remain compliant and operable for the duration of their useful life. For logistics managers, insights into lessor strategies and fleet availability assist in negotiating favorable lease terms and securing reliable transport capacity.
The report digs deeper into application-specific demands, examining how different industries utilize leased railcars. Whether for agricultural transport, industrial and energy sectors, or bulk commodity movement, the requirements for railcar specifications and lease durations vary. Our analysis covers these operational nuances, providing a blueprint for matching fleet assets to end-user needs. This granularity is essential for minimizing downtime and maximizing asset utilization rates.
Furthermore, the geographic distribution of demand plays a pivotal role in strategic planning. While global growth is evident, regional nuances dictate where opportunities are most potent. Understanding the specific market sizes and growth rates across North America, Europe, Asia Pacific, and other regions allows for a balanced portfolio approach. It helps organizations avoid over-concentration in saturating markets while identifying high-potential areas for expansion.
Railcar Leasing Market
Accessing the Full Intelligence
This overview provides a snapshot of the strategic landscape, highlighting the key players, regulatory pressures, and growth trends that define the railcar leasing market today. However, the complexity of the market requires a depth of analysis that goes beyond high-level summaries. To make informed decisions regarding fleet composition, lease structuring, and market entry or expansion, you need the complete dataset and expert analysis contained in our full market research report.
The full study delivers detailed segmentation data, precise revenue projections for specific regions and applications, and an exhaustive examination of the competitive environment. It offers the actionable intelligence necessary to build robust business cases, negotiate from a position of strength, and anticipate market shifts before they become industry-wide trends.
We invite you to explore the comprehensive findings of our Railcar Leasing Market study. By accessing the full report, you will equip your leadership team with the precise tools needed to navigate the complexities of 2026 and beyond. Ensure your strategy is built on data, not assumptions. Visit our source page to download the complete intelligence and secure your organization's position in the evolving rail economy.
For detailed analysis of this topic, please visit the official page: Railcar Leasing Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com
PW Consulting: Serial Device Server Market to Reach $317.3M by 2032 at 6.5% CAGR
By PW Consulting, 2026-09-16
Beyond Connectivity: Unlocking Strategic Value in the Serial Device Server Market (2026–2032)
The Critical Infrastructure Layer in a Legacy-Heavy World
Serial device servers sit at the intersection of legacy industrial hardware and modern IP networks—a position that makes them indispensable for enterprises managing brownfield automation, remote telemetry, and multi-vendor equipment integration. As industries accelerate their transition toward secure, centralized, and cloud-ready architectures, the devices that bridge RS-232, RS-422, and RS-485 endpoints to Ethernet and Wi-Fi backbones are experiencing sustained demand. Our newly released Serial Device Server Market research provides a comprehensive commercial and technical intelligence layer designed to inform capital allocation, product roadmap decisions, and competitive positioning through 2032.
The market’s trajectory reflects a structural shift rather than a temporary cycle. Revenue reached an estimated 205.0 million USD in the base year of 2025, up from approximately 188.99 million USD in 2024 and 185.99 million USD in 2023, following a consistent upward path from 150.0 million USD in 2020. This growth curve underscores the durability of serial-to-Ethernet conversion in industrial control, data acquisition, remote management, and point-of-sale ecosystems, even as IT departments invest heavily in all-IP alternatives. The forecast period from 2026 to 2032 projects a compound annual growth rate of 6.5 percent, with total revenue anticipated to rise from roughly 225.84 million USD in 2026 to 317.3 million USD by 2032. These figures are not merely projections—they form the foundation for capacity planning, vendor negotiation, and risk-adjusted investment strategies.
For decision-makers navigating procurement cycles, product development, or market entry, this research delivers what high-level summaries cannot: a granular view of demand drivers, technology migration patterns, regulatory touchpoints, and the competitive behaviors shaping pricing, feature sets, and channel influence. The analysis is deliberately structured to support executive-level prioritization while preserving the depth required by engineering, supply chain, and regulatory teams.
Structural Demand Drivers: Why Serial Device Servers Remain Strategically Resilient
A central theme emerging from our analysis is the persistence of serial protocols in environments where reliability, determinism, and cost-effective interoperability outweigh the pull of full IP replacement. Industrial control systems, data acquisition networks, remote management deployments, and point-of-service infrastructure all rely on serial interfaces for legacy compatibility, field-hardened performance, and simplified wiring topologies. Rather than displacing these devices, modernization initiatives are increasing their strategic value by demanding secure gateways, centralized fleet management, and protocol-agnostic bridging.
Several dynamics are reinforcing this demand profile. First, the coexistence of operational technology and information technology stacks means that serial endpoints must be integrated into network architectures without disrupting uptime or requiring wholesale equipment replacement. Second, security expectations have evolved from basic connectivity to encrypted serial-to-IP tunnels, centralized authentication, and audit-ready management interfaces. Third, environmental and transportation-grade certifications are becoming gating factors in bidding processes for public infrastructure, manufacturing automation, and outdoor telemetry deployments. These factors collectively elevate the serial device server from a simple connectivity add-on to a programmable gateway component within broader edge networks.
The research also examines how network infrastructure economics influence deployment velocity. Ethernet interface cards and fiber-optic infrastructure remain primary cost drivers in serial device server network deployments, which means total cost of ownership is shaped not only by the gateway hardware itself, but by the surrounding physical layer, cabling, and integration labor. This reality has important implications for procurement strategy, vendor bundling, and the evaluation of modular platforms such as SFP-based hot-swappable designs that can delay or reduce physical-layer reinvestment.
Market Size, Growth Trajectory, and What the Numbers Really Signal
The macro-level trajectory provides a reliable anchor for strategic planning. After expanding from 158.23 million USD in 2021 and 170.18 million USD in 2022, the market crossed the 185 million USD threshold in 2023 and continued its ascent to 205.0 million USD in 2025. The short-term forecast indicates 225.84 million USD in 2026, followed by a slight moderation in year-over-year momentum before resuming steady growth to 227.25 million USD in 2027, 248.41 million USD in 2028, 260.47 million USD in 2029, 285.73 million USD in 2030, 298.04 million USD in 2031, and 317.3 million USD in 2032.
For strategy teams, the more important takeaway is the shape of this curve. The data suggests a market that is not only growing but maturing in its demand patterns: growth is increasingly tied to secure management, ruggedized industrial form factors, modular network compatibility, and certification readiness. Companies that treat serial device servers as commoditized pass-through hardware risk underpricing value-added features and missing higher-margin opportunities in industrial automation, remote fleet management, and hazardous-location deployments. Conversely, organizations that align product roadmaps with the specific integration requirements of brownfield environments can capture disproportionate share in segments where interoperability and compliance create meaningful barriers to substitution.
Our research deliberately avoids oversimplified regional or application-level breakdowns in this overview because the strategic value lies in how those segments interact with pricing, certification requirements, and channel dynamics. The full report details how demand clusters across geographies and application types, which subsegments are growing fastest in absolute and relative terms, and where saturation risk or substitution pressure is most likely to emerge.
Competitive Landscape: Differentiated Platforms in a Concentrated Environment
Market concentration provides an early signal of competitive intensity. The three largest players account for approximately 52.8 percent of revenue, while the five largest reach about 64.7 percent. This distribution indicates a market with established incumbents, meaningful product differentiation, and room for specialized challengers that compete on security, ruggedization, or form-factor innovation. Understanding how the leading vendors position their offerings is essential for both competitive benchmarking and partnership evaluation.
Pepperl+Fuchs, headquartered in Mannheim, Germany, emphasizes serial device server solutions aimed at industrial automation and transportation integration. Its ICDM-RX/TCP series delivers DIN-rail mounted RS-232/422/485 to Ethernet conversion with TCP/UDP socket services, and the inclusion of NEMA TS2 certification options expands its relevance for transportation-grade and industrial Ethernet environments. A product update in August 2025 extended this family with additional NEMA TS2 certification options, reinforcing the company’s focus on compliance-sensitive deployments.
Comtrol, operating as Pepperl+Fuchs Comtrol with headquarters in Twinsburg, Ohio, USA, focuses on secure serial-to-IP gateways. The DeviceMaster PRO/RTS/Serial Hub family supports COM/TTY/TCP configurations and has been strengthened with enhanced SSL/SSH encryption. In March 2025, the company updated the series with SSL/SSH management and serial data stream encryption for secure serial-to-IP connectivity, a move that reflects rising security expectations in industrial and enterprise edge contexts.
Digi International, based in Minneapolis, Minnesota, USA, continues to position its Digi Connect EZ TS and Connect SP series as secure serial device servers for legacy-to-IP conversion. The portfolio’s RealPort drivers and centralized management capabilities support organizations seeking to standardize remote access and device administration across distributed installations. In May 2026, Digi launched Digi Connect EZ TS 4-port and 8-port secure serial device servers with enhanced centralized management for modern IP network transitions, signaling continued investment in fleet management and migration-friendly architectures.
Moxa, headquartered in Taipei, Taiwan, targets industrial RS-232/422/485 to Ethernet conversion with the NPort 5100/5110 and IA5000 series. These platforms emphasize surge protection and hazardous-location certifications, making them relevant for demanding field environments. A February 2025 update improved the NPort IA5000-G2 DIN-rail and IA5000A industrial series with enhanced surge protection for hazardous environments, reinforcing Moxa’s focus on durability and compliance in industrial settings.
Advantech, also based in Taipei, Taiwan, offers the EKI-1521/1522/1524 series of industrial Ethernet/serial device servers with virtual COM support and LAN redundancy. This positioning speaks to customers who prioritize operational resilience, seamless device emulation, and network failover in automation and control environments.
Patton, headquartered in Gaithersburg, Maryland, USA, introduced a notable infrastructure-oriented product in April 2025 with the launch of the Connect-IT CIT-SFP SFP-based hot-swappable RS-232/422/485 serial device server for legacy-to-IP bridging. The SFP-based approach addresses network flexibility and physical-layer economics by enabling modular fiber or copper connectivity without full hardware replacement, an increasingly important consideration as deployment costs are scrutinized.
Silex Technology, based in Tokyo, Japan, provides the SD-300/SD-320 series of wired and wireless RS-232 serial device servers for Ethernet and Wi-Fi network connectivity. This wireless extension broadens the addressable use cases for serial endpoints where cabling constraints or temporary deployments make Wi-Fi connectivity advantageous.
Sealevel Systems, headquartered in Liberty, South Carolina, USA, focuses on the SeaLINK series of Ethernet serial servers supporting up to 16 RS-232/422/485 ports for industrial data acquisition and control systems. The multi-port architecture is particularly relevant for centralized monitoring and control applications that must aggregate many serial endpoints without proliferating gateway devices.
PLANET Technology, also headquartered in Taipei, Taiwan, offers the ICS-2100T/2200T/2400T series of industrial 1/2/4-port RS-232/422/485 to Fast Ethernet serial device servers with wide-temperature operation. This wide-temperature capability supports deployment in environments where thermal extremes would disqualify commercial-grade hardware.
The competitive picture is not just about product portfolios; it is about how vendors translate certification readiness, security, modularity, and environmental hardening into defensible pricing and customer lock-in. The research maps these positioning strategies and identifies the operational implications for buyers evaluating total cost of ownership, support requirements, and lifecycle compatibility.
Regulatory, Certification, and Deployment Dynamics That Shape Commercial Outcomes
Regulations and certifications are not side conditions; they are commercial gating factors that influence bid eligibility, deployment timelines, and regional expansion feasibility. In the United States, all active manufacturers of serial device server products must comply with FCC Part 15 rules for unintentional radiators to prevent harmful interference, a requirement that can affect design choices, testing cycles, and market entry sequencing. In the European Economic Area, serial device server equipment sold into the market requires CE marking under relevant EMC and safety directives, adding conformity assessment obligations that influence product planning and documentation.
Serial Device Server Market
Safety and industrial-use certifications further shape procurement and engineering decisions. Industrial serial device server models are commonly UL 61010-1 listed for safety in laboratory and industrial use, an assurance that matters in environments where equipment must meet recognized electrical safety standards. For transportation and public infrastructure applications, NEMA TS2 certification addresses spectrum and environmental compliance requirements, making it a strategic differentiator for vendors pursuing bids in transit and municipal deployments.
Together, these regulatory and certification layers contribute to a market in which product compliance is a source of competitive advantage rather than a back-office task. The report integrates these dynamics into the broader analysis of market behavior, showing how certification roadmaps, testing lead times, and regional conformity requirements interact with product launches, distributor selection, and customer segment prioritization.
What the Report Delivers: Operational Intelligence for 2026 Decisions
This research is designed as a decision-support instrument rather than a static market summary. It combines market sizing and growth projections with actionable qualitative analysis across segmentation, competitive behavior, and deployment dynamics. The core deliverable includes a structured assessment of external and embedded serial device server categories, an exploration of application-side demand patterns across industrial control systems, data acquisition, remote management, point-of-sale systems, and other use cases, and a detailed view of regional demand distribution without reducing the analysis to simplistic percentage tables.
Beyond segmentation, the report examines product evolution patterns, including secure serial-to-IP gateways, DIN-rail industrial form factors, multi-port aggregation platforms, SFP-based hot-swappable bridging, wide-temperature operation, surge protection for hazardous environments, and wireless serial connectivity. It also addresses the commercial significance of centralized management, virtual COM compatibility, LAN redundancy, RealPort-style driver ecosystems, and encryption frameworks such as SSL/SSH. These feature dimensions are analyzed in relation to pricing architecture, differentiation potential, and customer acceptance in regulation-sensitive or environment-sensitive deployments.
Competitive analysis extends beyond product descriptions to include launch timing, update cadence, and strategic intent. Recent developments illustrate how the market is evolving: Patton’s April 2025 launch of the CIT-SFP SFP-based hot-swappable serial device server for legacy-to-IP bridging; Digi International’s May 2026 launch of Digi Connect EZ TS 4-port and 8-port secure serial device servers with enhanced centralized management; Comtrol’s March 2025 update to the DeviceMaster PRO/RTS series with SSL/SSH management and serial data stream encryption; Pepperl+Fuchs’ August 2025 extension of the ICDM-RX/TCP family with NEMA TS2 certification options; and Moxa’s February 2025 update to the NPort IA5000-G2 and IA5000A series with enhanced surge protection for hazardous environments. These events are not isolated product news; they reflect broader strategic bets on security, modularity, ruggedization, and compliance-enabled market access.
How to Use This Research for 2026 Planning
For executives and analysts, the report offers a practical framework for several high-stakes decisions. Procurement leaders can use the segmentation and competitive analysis to structure vendor evaluations around security, management, ruggedization, and certification readiness rather than unit price alone. Product and engineering teams can reference the technology migration patterns to prioritize virtual COM, centralized management, encryption, and modular network compatibility in roadmaps. Business development teams can identify where certification requirements and environmental hardening create entry barriers that protect incumbents or where wireless and multi-port platforms open new addressability. Risk and compliance teams can integrate FCC Part 15, CE marking, UL 61010-1, and NEMA TS2 considerations into market-entry and sourcing plans with a clearer view of lead times and documentation requirements.
The analysis also supports scenario planning by connecting market growth, concentration levels, and infrastructure cost realities to potential shifts in pricing, bundling, and channel influence. Because Ethernet interface cards and fiber-optic infrastructure remain primary cost drivers in network deployments, total project economics often depend on how serial device server platforms align with existing or planned physical-layer investments. The report provides the context needed to evaluate whether modular, hot-swappable, or multi-port solutions offer better lifecycle economics in specific deployment profiles.
Conclusion: From Market Data to Decision Advantage
The Serial Device Server Market is growing within a 6.5 percent CAGR framework and is projected to move from 225.84 million USD in 2026 to 317.3 million USD by 2032, but the strategic opportunity lies in understanding why that growth is happening, where value is being captured, and how competitive and regulatory forces shape customer choices. This research translates those dynamics into an actionable intelligence base for procurement, product strategy, market entry, and competitive positioning.
SerDes Market
The overview above establishes the analytical direction and the breadth of coverage, while the full report provides the structured detail required to support discrete decisions across regions, applications, product types, and competitive scenarios. For teams preparing for 2026 planning cycles, the complete analysis offers the missing layer between high-level market narratives and operational execution—enabling more confident capital allocation, vendor selection, and roadmap prioritization in a market where connectivity, compliance, and industrial reliability all converge.
For detailed analysis of this topic, please visit the official page: Serial Device Server Market
Lacy Lee
Senior Marketing Manager
sales@pmarketresearch.com
00852-95632430
PW Consulting: www.pmarketresearch.com